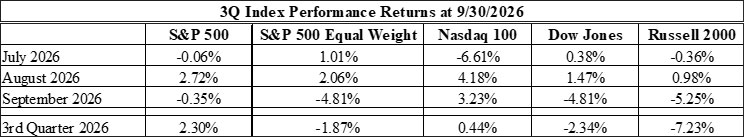
The third quarter of 2026 offered another reminder that the stock market and media headlines do not always move in the same direction. Despite persistent inflation, higher interest rates and continued uncertainty in the Middle East, the S&P 500 Index finished the quarter just over 2% higher. Results, however, were far more volatile monthly and less consistent overall beneath the surface as seen in the following table:
The market’s biggest challenge remains inflation, though the latest readings offered some encouragement. The Federal Reserve’s preferred measure, the Personal Consumption Expenditures price index, increased 3.4% over the twelve months ending in August. Excluding food and energy, prices rose 3.0%. Both figures were below expectations but remained above the Fed’s 2% objective. Progress is welcome, though we believe it is too early to consider the inflation problem resolved.
As we discussed last quarter, the possibility of higher interest rates had begun to influence the bond market. That possibility became reality in September when the Federal Open Market Committee raised its benchmark rate by one-quarter percentage point to a range of 3.75% to 4.00%. Chairman Kevin Warsh emphasized that the economy remained resilient, but that inflation was not moving toward the Fed’s target quickly enough. The decision reinforced our belief that investors should not take a return to lower interest rates for granted.
Longer-term borrowing costs also moved higher, with the yield on the ten-year U.S. Treasury reaching approximately 5.3% at quarter-end. From our perspective, this creates both challenges and opportunities. Higher yields offer more attractive income on newly purchased bonds, but they also raise financing costs for businesses and households. In evaluating investments, we continue to place importance on manageable debt, dependable cash flow and a company’s ability to fund its operations without relying heavily on favorable credit markets.
Meanwhile, the enormous investment associated with artificial intelligence remains an important economic and market theme. Last quarter, we noted the attention being paid to the “picks and shovels” businesses supplying the hardware and infrastructure behind AI development. That spending continues to have implications beyond technology stocks. The Fed cited major technology companies’ demand for financing as one contributor to rising longer-term yields. Our task is not simply to identify where money is being spent, but to judge which businesses can turn that spending into durable profits—and whether their share prices already assume too much success.
The broader economy continues to provide reasons for both confidence and caution. At its September meeting, the Fed described domestic spending as resilient and business investment as robust. The September employment report, released in early October, subsequently showed a more subdued pace of hiring. We view these developments as a reason to watch the direction of the economy carefully, rather than draw a sweeping conclusion from any single report.
Looking ahead, we remain willing to invest, but selective about the expectations for which we are willing to pay. We do not need to predict the next Fed decision, the next geopolitical development or the next market favorite to make sound investment judgments. Instead, we will continue to examine businesses individually, test their earnings prospects and look for opportunities where price and long-term value appear meaningfully different. Our confidence rests less on a forecast for the next few months than on the ability of well-run businesses to adapt and create value over time.